Every time mortgage rates tick up or down, your phone probably floods with notifications, ads, and “expert” predictions. If you’ve noticed “mortgage rates today” trending on search engines, you’re not alone—and there’s a solid reason millions of Americans are suddenly paying attention. Whether you’re a homeowner, a renter, or someone who’s been sitting on the fence about buying, mortgage rate movements ripple through the entire economy in ways that directly affect your paycheck, your savings strategy, and your long-term money plan.
The thing is, most people think mortgage rates only matter if they’re actively house hunting. That’s not quite right. Mortgage rates are a window into what the Federal Reserve is doing with interest rates across the board—and that impacts everything from your credit card APR to your savings account yield. Understanding what’s happening in the mortgage market right now gives you a real edge in making smarter money decisions today, not someday.
Let’s break down why mortgage rates are getting so much attention, what’s really driving them, and most importantly, what you should actually do about it.
What Mortgage Rates Really Tell You About the Economy
Mortgage rates aren’t set by any single person or committee—they’re determined by a complex dance between the Federal Reserve’s decisions, bond markets, inflation, and job market health. When mortgage rates rise sharply, it usually signals that lenders are nervous about inflation or that the Fed is actively raising its benchmark interest rate to cool down the economy. When they drop, it often means the opposite: the Fed is cutting rates to stimulate borrowing and spending.
Here’s what matters to you: the same forces that move mortgage rates also move rates on savings accounts, credit cards, auto loans, and personal loans. So when you see mortgage rates making headlines, pay attention. It’s telling you something important about the direction of money in your life.
Think of mortgage rates as a thermometer for the entire lending market. They’re one of the first things to move when conditions shift, so they’re a useful early warning system.
Three Ways Rising Mortgage Rates Affect Your Money Right Now
Your Savings Account Suddenly Becomes More Valuable
Here’s some genuinely good news: when mortgage rates rise, banks typically raise interest rates on savings accounts, money market accounts, and certificates of deposit (CDs) too. If you’ve been parking cash in a standard savings account earning near-zero interest, a rising-rate environment is your chance to actually get paid for keeping your money safe.
What to do: Check what your current savings account is paying. If it’s less than 0.5%, you’re leaving money on the table. High-yield savings accounts now routinely offer 4-5% APY or higher. Moving your emergency fund or short-term savings there can put real money back in your pocket—sometimes hundreds of dollars per year—with zero risk.
Your Credit Card Debt Gets More Expensive
The flip side: if you carry a credit card balance, rising rates hurt. Most credit cards charge variable interest rates tied to the prime rate, which moves with Fed decisions. When the Fed signals that rates are staying high or going higher, credit card companies increase their rates almost immediately.
What to do: If you’re carrying credit card debt, this is your signal to accelerate payoff. The math is now working against you—every month you carry a balance, you’re paying more in interest than you would have a year ago. Even a small increase in your monthly payment toward credit cards can save you hundreds in interest charges over time.
Refinancing Your Home Loan Becomes Less Appealing (or a Missed Window)
If you own a home and locked in a mortgage rate below 4% in recent years, you’re in a good position—and you should protect it. Higher mortgage rates mean refinancing no longer makes financial sense for most homeowners. If you were thinking about refinancing but haven’t pulled the trigger yet, each rate increase makes it less attractive.
What to do: If you have a mortgage, know your current rate and don’t automatically assume refinancing is worth it anymore. Work the math: figure out how long it’ll take for monthly savings to cover refinancing costs, and only proceed if you plan to stay in the home long enough to break even.
How Rising Mortgage Rates Reshape the Housing Market
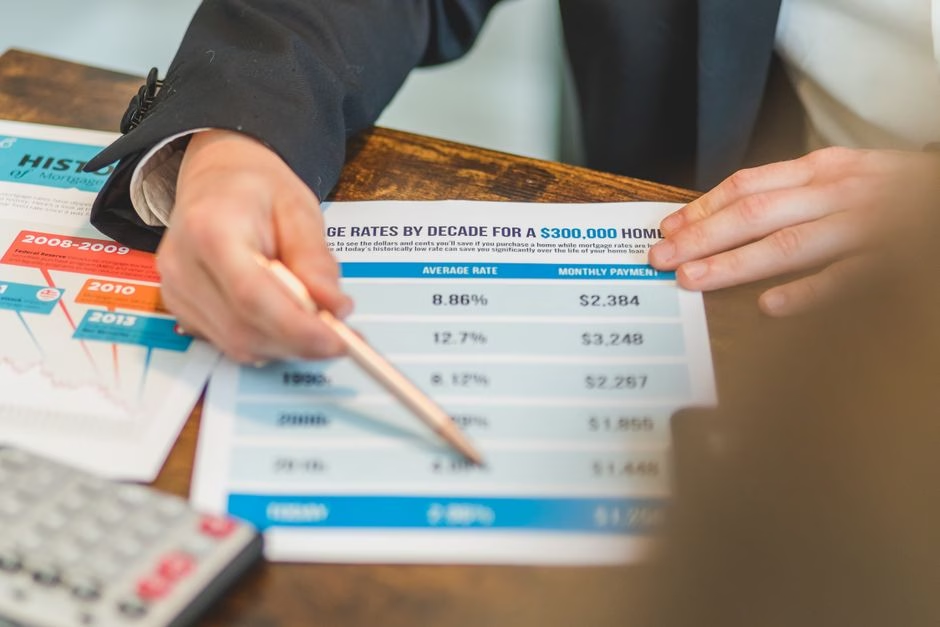
When mortgage rates climb, the math changes for buyers. A $500,000 home with a 3% mortgage rate costs roughly $2,100 per month (principal and interest only). That same home at 7% costs roughly $3,300 per month. For most Americans, that’s the difference between “affordable” and “not happening.”
Higher mortgage rates cool down buyer demand, which means sellers often have to lower prices or wait longer to sell. For renters, this can actually be good news: lower home prices might mean lower rent eventually, since landlords price their rentals based on what homeowners’ carrying costs are.
The practical takeaway: if you’ve been priced out of buying, don’t panic. A higher-rate environment often brings housing prices down, which can make entry points better for first-time buyers. Why Mortgage Rates Are Trending Now: What It Means for Your Home Goals breaks this down further if you’re actively considering a purchase.
The Most Common Mistake: Ignoring the Broader Money Picture
Most people focus on mortgage rates in isolation—they either panic if they’re high or celebrate if they’re low. But here’s what actually matters: mortgage rates move as part of a larger shift in interest rates across the entire economy.
When you see mortgage rates trending, use it as a prompt to audit your entire money situation, not just your home plans. Are you getting paid on your savings? Is your debt becoming more expensive? Do you need to refinance anything while rates are at a certain level? Is your emergency fund sufficient if times get tougher?
The people who come out ahead during rate cycles aren’t the ones who obsess over mortgage rates—they’re the ones who use the trend as a signal to review and optimize their full financial picture.
What You Should Do Today
Step 1: Check your savings rate. Log into your savings account and see what interest rate you’re earning. If it’s below 4%, move money to a high-yield option. This takes 10 minutes and could earn you money every single month going forward.
Step 2: List any variable-rate debt you have. Credit cards, home equity lines of credit (HELOCs), and adjustable-rate mortgages all have rates tied to market conditions. Know what you’re paying and whether your rate has changed recently.
Step 3: If you own a home, know your mortgage rate. Pull your paperwork or log into your servicer’s website. Compare it to current market rates just to understand where you stand. You don’t need to act on it—just know the facts.
Step 4: Ask yourself one honest question: “Am I better off borrowing or saving right now?” Higher rates make saving more attractive and borrowing more expensive. This should influence your money priorities for the next few months.
Mortgage rates trending doesn’t have to stress you out. It’s actually a useful reminder to check in on your money and make sure you’re positioned well for whatever’s coming next.