Housing is typically the single largest expense in any American household budget, consuming anywhere from 30% to over 50% of monthly take-home pay. For decades, standard financial advice insisted on the same slow path: cut back on small luxuries, save aggressively, and wait years to accumulate a massive 20% down payment. But if you want to eliminate your single biggest monthly bill right away, a much faster real estate strategy exists.
Learning how to house hack a duplex with an FHA loan enables you to leverage government-backed financing to buy a multi-family property with as little as 3.5% down. By moving into one side and renting out the other, your tenant’s monthly rent can cover most—or even all—of your mortgage payment. Instead of sending thousands of dollars to a landlord every month, you build home equity while drastically lowering your living expenses.
This comprehensive guide walks you through the step-by-step process of getting approved, running the math accurately, selecting the right property, and managing your first tenant without taking on unnecessary stress.
—
What Is House Hacking and Why Does an FHA Loan Work So Well?
House hacking is the practice of purchasing a residential property, occupying part of it as your primary residence, and renting out the remaining units or rooms to generate rental income. While you can house hack single-family homes or larger multi-family properties, a two-unit property—a duplex—offers the ideal balance of privacy, financial return, and ease of management for beginners.
The real magic of this strategy comes from pairing a duplex with a loan backed by the Federal Housing Administration (FHA). Standard conventional loans for non-owner-occupied investment properties typically require a 15% to 25% down payment and higher credit score thresholds. An FHA loan, however, is designed to make homeownership accessible.
Key Advantages of FHA Financing for a Duplex
- Low Down Payment Requirement: You only need 3.5% down if your credit score is 580 or higher. On a $300,000 duplex, that is an upfront down payment of $10,500 compared to $60,000 for a traditional investment mortgage.
- Using Future Rent to Qualify: Mortgage lenders generally allow you to use up to 75% of the projected rental income from the second unit to boost your qualifying income, helping you pass debt-to-income (DTI) checks.
- Competitive Interest Rates: Because FHA loans carry government backing, interest rates are often equal to or lower than conventional residential mortgages.
- Owner-Occupancy Rule: FHA rules require you to live in one of the units as your primary residence for at least 12 months. After one year, you are free to move out, keep the duplex as a full rental, or refinance into a conventional loan.
—
Step 1: Run the Real Math Before You Start Shopping
The most common trap new real estate buyers fall into is focusing solely on the purchase price and ignoring the total cost of property ownership. To live for free—or close to it—you must calculate your full monthly outlay versus expected rental revenue.
Understanding Your PITI + MIP Output
Your total monthly mortgage payment consists of five distinct components:
- Principal: The portion paying down the balance of your loan.
- Interest: The cost of borrowing money.
- Property Taxes: Local county/city taxes assessed on the property value.
- Homeowners Insurance: Required hazard insurance covering the structure.
- Mortgage Insurance Premium (MIP): Mandatory for all FHA loans, including both an upfront fee (usually 1.75% of the loan amount, rolled into the total loan) and an annual monthly fee.
Accounting for Maintenance, Vacancy, and Reserves
Never assume your unit will be occupied 365 days a year or that nothing will break. Sustainable real estate investors budget for operational overhead:
- Vacancy Factor (5% to 8%): Set aside a fraction of monthly rent to cover turnover periods between tenants.
- Repairs & Maintenance (5% to 10%): Reserve funds for ongoing upkeep, such as plumbing fixes or painting.
- Capital Expenditures / CapEx (5% to 10%): Long-term savings for major replacement items like roofs, HVAC systems, and hot water heaters.
A Real-World Duplex Math Example
Imagine purchasing a side-by-side duplex for $350,000.
- Down Payment (3.5%): $12,250
- Total Estimated PITI + MIP Payment: $2,450 / month
- Rent Collected from Unit B: $1,800 / month
- Your Net Out-of-Pocket Housing Cost: $650 / month
In this realistic scenario, instead of paying $1,800 or $2,000 a month to rent a standard apartment in your city, your housing expense drops to $650. You save over $1,200 every single month while simultaneously paying down your own mortgage principal and benefiting from long-term real estate appreciation.
—
Step 2: Get Pre-Approved and Prepare Your Financial Safety Net
Before looking at property listings, secure an official pre-approval letter from a mortgage lender experienced with FHA multi-family loans.
What You Need for FHA Approval
- Credit Score: A minimum score of 580 qualifies for the 3.5% down payment. Scores between 500 and 579 generally require 10% down.
- Debt-to-Income (DTI) Ratio: Lenders prefer your total debt obligations (including the new mortgage minus credited rental income) to remain under 43% to 50% of your gross monthly income.
- Two Years of Stable Income: W-2 tax forms, pay stubs, and employment verification. Self-employed borrowers need two full years of tax returns.
- Cash Reserves: In addition to the 3.5% down payment, expect 2% to 4% in closing costs (appraisal, title fees, escrow setup). Lenders also prefer to see 2 to 3 months of mortgage payments remaining in liquid cash reserves after closing.
Before locking up your liquid savings into a real estate transaction, establish a firm personal reserve fund. Unexpected maintenance expenses or sudden economic shifts can impact your personal finances quickly. If you are balancing savings targets while protecting your overall safety net, reviewing how to prepare financially for a layoff offers actionable steps for structuring liquid emergency reserves alongside major investments.
—
Step 3: Target the Right Duplex Property
Not every two-unit building makes a good house hack. When scanning listings on the MLS or evaluating potential properties, keep several structural and financial factors top of mind:
1. Utility Separation
Verify whether electric, gas, and water meters are split independently between both units. If utilities are combined on a single meter, you will either have to pay the full utility bill yourself or install costly sub-meters. Separate meters allow tenants to pay their own utility bills directly to service providers.
2. Layout and Privacy
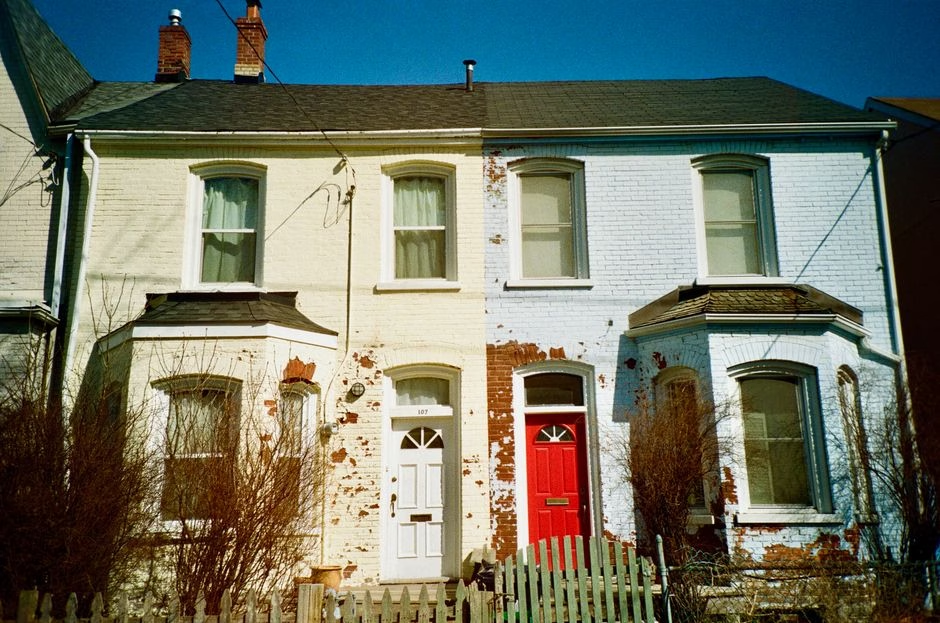
Look for properties with physical separation between living quarters. Side-by-side duplexes with separate driveways, distinct front entrances, and private outdoor spaces are generally easier to manage and command higher rental rates than top-bottom duplexes with shared internal stairwells.
3. FHA Property Guidelines (The “FHA Appraisal”)
FHA loans require strict property condition standards to ensure safety and structural soundness. The appraiser will look closely at:
- Roof condition (must have remaining functional life)
- Absence of peeling paint (critical for homes built before 1978 due to lead paint regulations)
- Operational heating, plumbing, and electrical systems
- Handrails on staircases and clear safety exits
If a seller’s property has severe deferred maintenance, an FHA loan may not close unless the seller agrees to repair those defects prior to closing.
—
Step 4: Screen Tenants and Run the Property Like a Business
The single biggest determining factor in whether your house hack feels like a financial dream or an operational nightmare is your tenant selection process. Living next door to your tenant makes thorough screening non-negotiable.
Establishing Objective Screening Criteria
Always establish fair, written, non-discriminatory screening criteria before listing your available unit for rent:
- Income Requirement: Require applicant gross monthly income to equal at least 3 times the monthly rent amount.
- Credit and Criminal Checks: Utilize online rental platforms (such as Zillow Rental Manager, Avail, or TurboTenant) to pull credit scores, eviction histories, and background reports.
- Landlord References: Contact previous landlords—specifically the landlord prior to their current one, as current landlords occasionally give glowing reviews just to get a problematic tenant to move out.
Setting Professional Boundaries
Because you will be living in the adjacent unit or upstairs apartment, establish firm professional boundaries from day one:
- Use Online Payment Portals: Never collect rent in cash or take physical checks at your front door. Require tenants to pay through an online portal or automated bank transfer.
- Communicate via Official Channels: Direct non-emergency communications (like repair requests or questions) through email or a dedicated tenant management app rather than casual text messages.
- Enforce Lease Terms Consistently: Charge late fees as written in your lease contract. Making exceptions early sets a precedent that payment deadlines are flexible.
—
The Most Common House Hacking Mistakes to Avoid
Even with low down payments and solid rental demand, first-time real estate investors can make predictable errors. Avoid these common traps:
- Overestimating Market Rent: Relying on overly optimistic rental estimates can leave you short on monthly cash. Research comparable properties currently rented in the immediate 1-mile radius using sites like Rentometer or local market listings.
- Failing to Budget for FHA Insurance Costs: Remember that FHA monthly mortgage insurance (MIP) remains for the entire life of an FHA 30-year loan if you put down less than 10%. You must factor this permanent monthly fee into your ongoing numbers until you refinance.
- Ignoring Local Landlord-Tenant Laws: Research local security deposit storage rules, notice-to-enter requirements, and lease termination laws in your state and municipality before signing a rental agreement.
—
The Exit Strategy: Building Long-Term Wealth After Year One
The true wealth-building potential of an FHA duplex house hack extends far beyond your first twelve months. Once you fulfill the mandatory 1-year owner-occupancy requirement under your FHA mortgage agreement, you have options:
- Stay and Enjoy Low Overhead: Continue living in your unit while saving the money you would have spent on rent toward retirement accounts, index funds, or future real estate investments.
- Move Out and Fully Rent the Building: Move into a new primary residence and lease out the unit you previously occupied. Now, both units generate rental income, transforming the property into a cash-flowing asset.
- Refinance into a Conventional Loan: Once your property builds 20% equity through market appreciation and monthly debt payoff, refinance the FHA mortgage into a conventional residential loan. This eliminates the monthly FHA Mortgage Insurance Premium (MIP), instantly boosting your monthly cash flow.
By utilizing an FHA loan to purchase a duplex, you replace your largest monthly liability—rent or a high mortgage—with an income-generating asset. With low capital required upfront, smart numerical analysis, and clear property management boundaries, house hacking remains one of the most reliable strategies for everyday Americans to build real net worth.
—
Are you considering house hacking a multi-family property in your area, or do you have questions about running the numbers on an FHA loan? Drop your thoughts or questions in the comments below!